

The National Electricity Market
Wholesale electricity prices decreased again in all NEM States in September. SA fell the most, down 47% to $38. VIC fell 39% to $37 while TAS fell 33% to $39. QLD and NSW decreased the least, down 5% and 14% respectively. Average prices ranged from below $40 in TAS, SA and VIC up to $65 in NSW.

Electricity Generation Mix
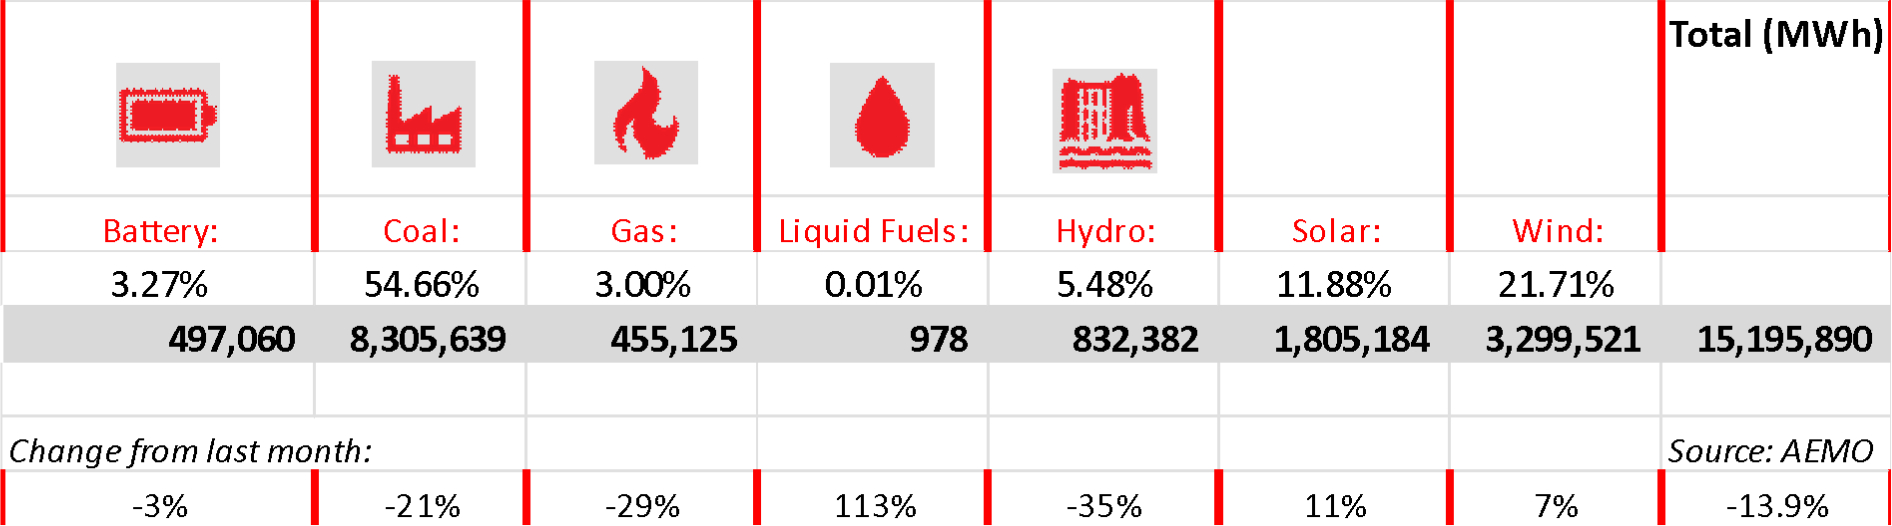
Total grid-scale generation for September decreased by 14% from August levels, indicating a significant reduction in operational demand, even after allowing for the fewer days in the month.
All generation types recorded significant falls, apart from wind and solar, which increased 7% and 11% respectively compared to last month.
Gas Generation
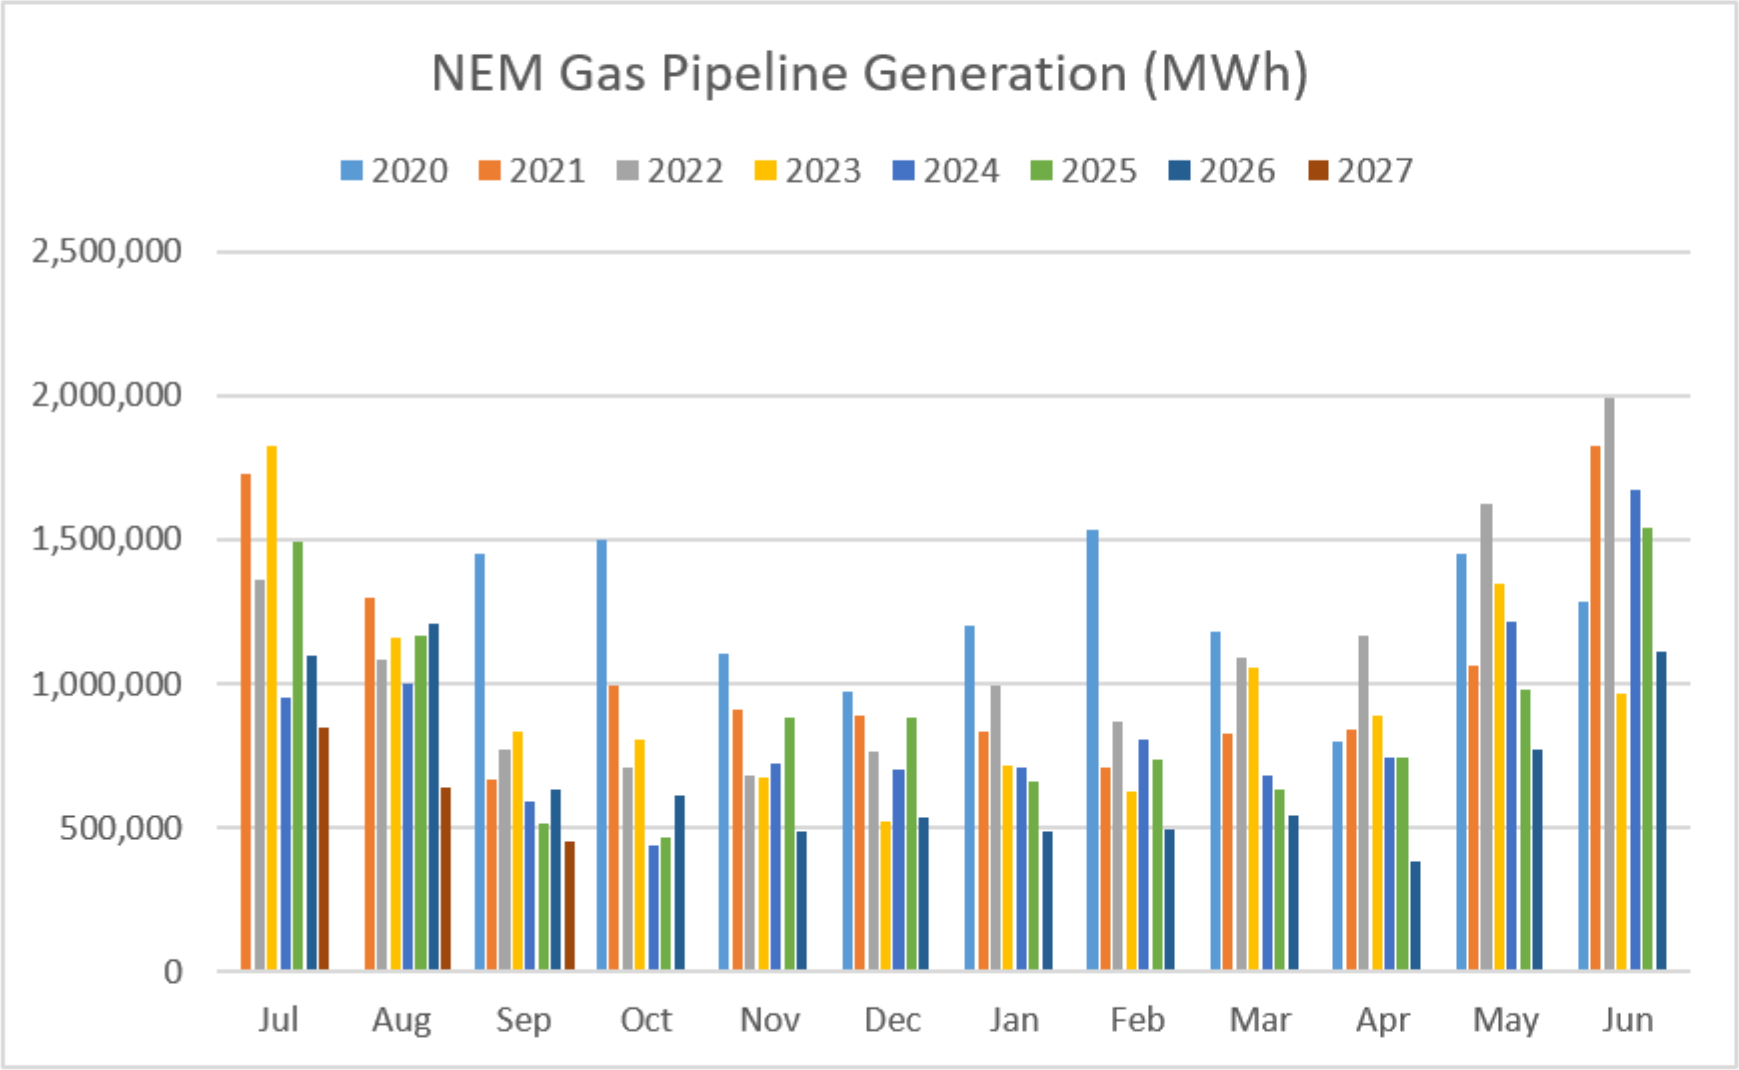
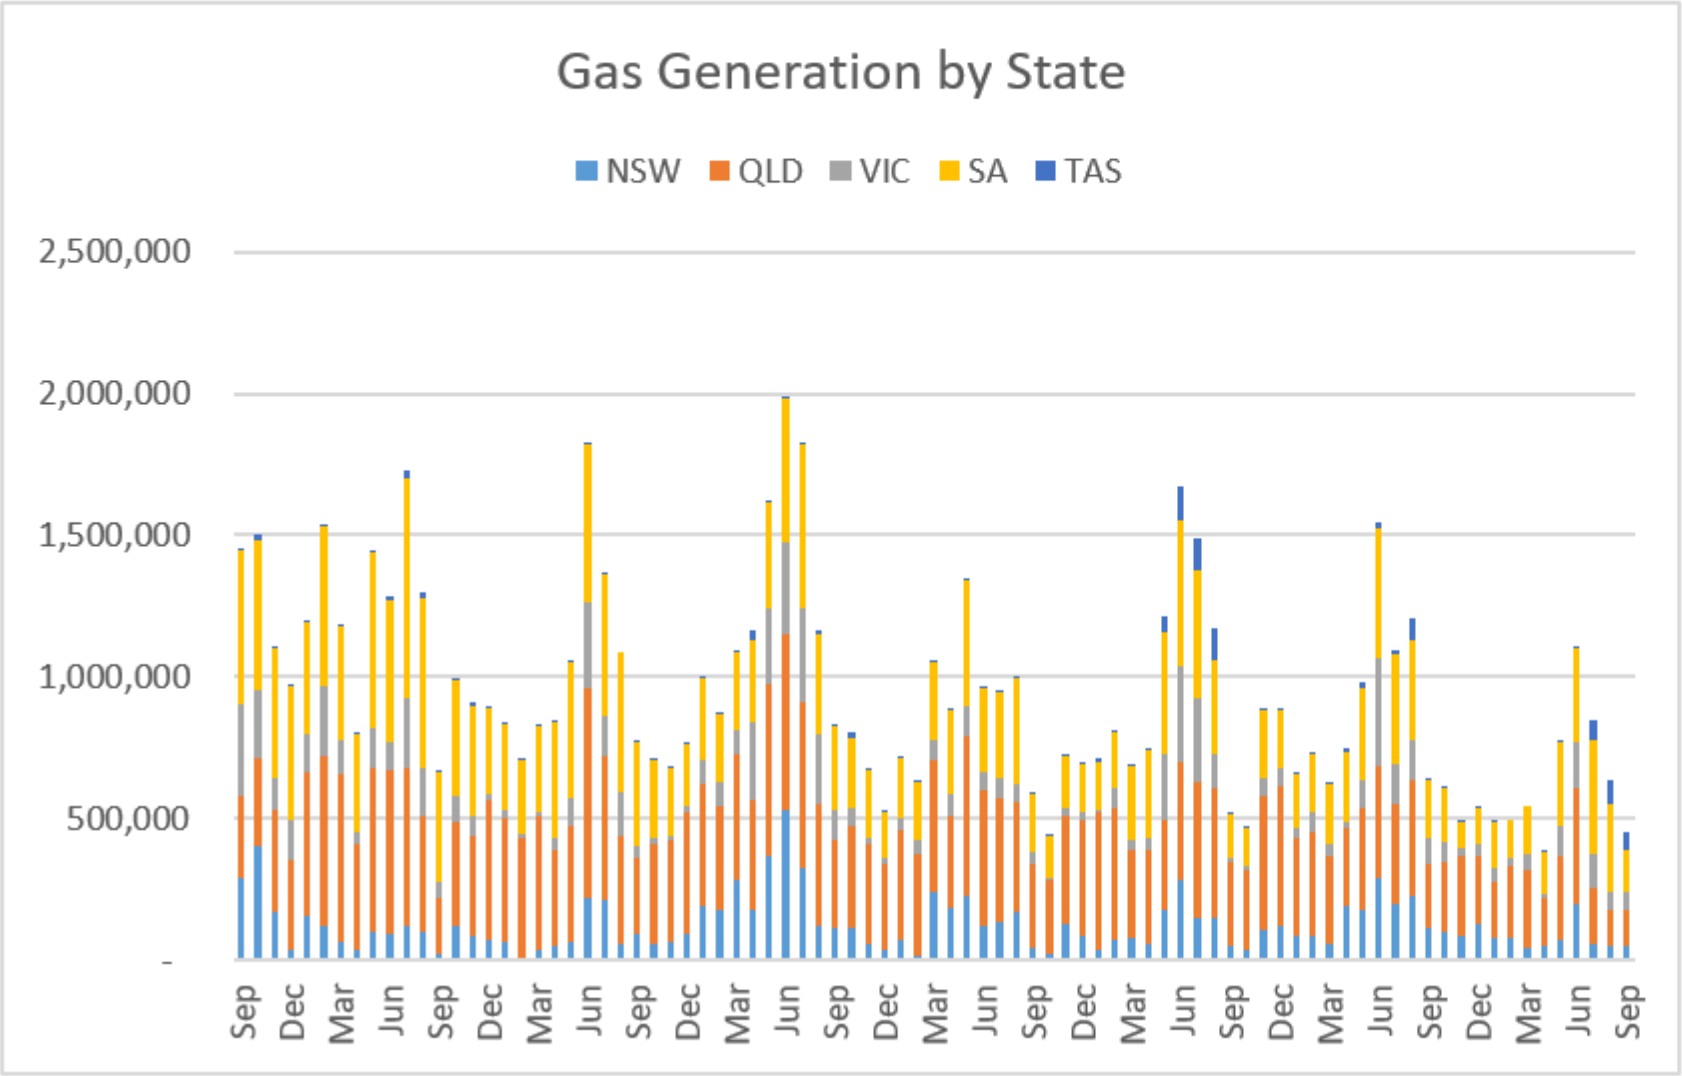
Gas generation decreased again in September – down another 29% compared to August. Compared with September 2025, gas generation was 28% lower.
Gas generation was down in all states apart from VIC (up 13%). SA was down 52% while TAS was down 30%, NSW 9% and QLD 1%.
Hydro Generation
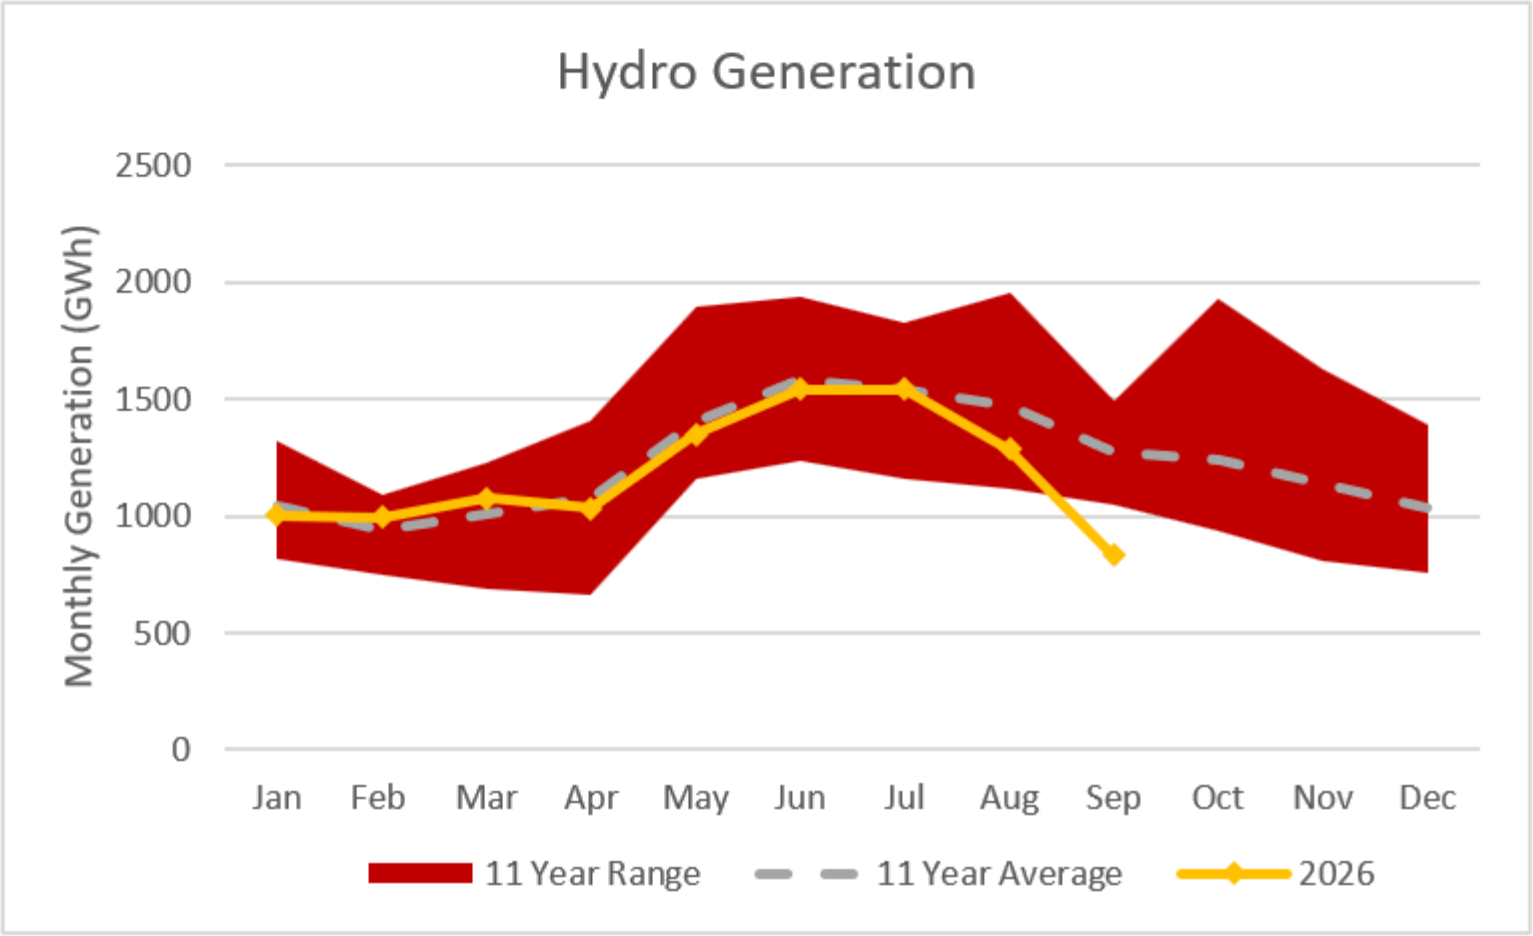
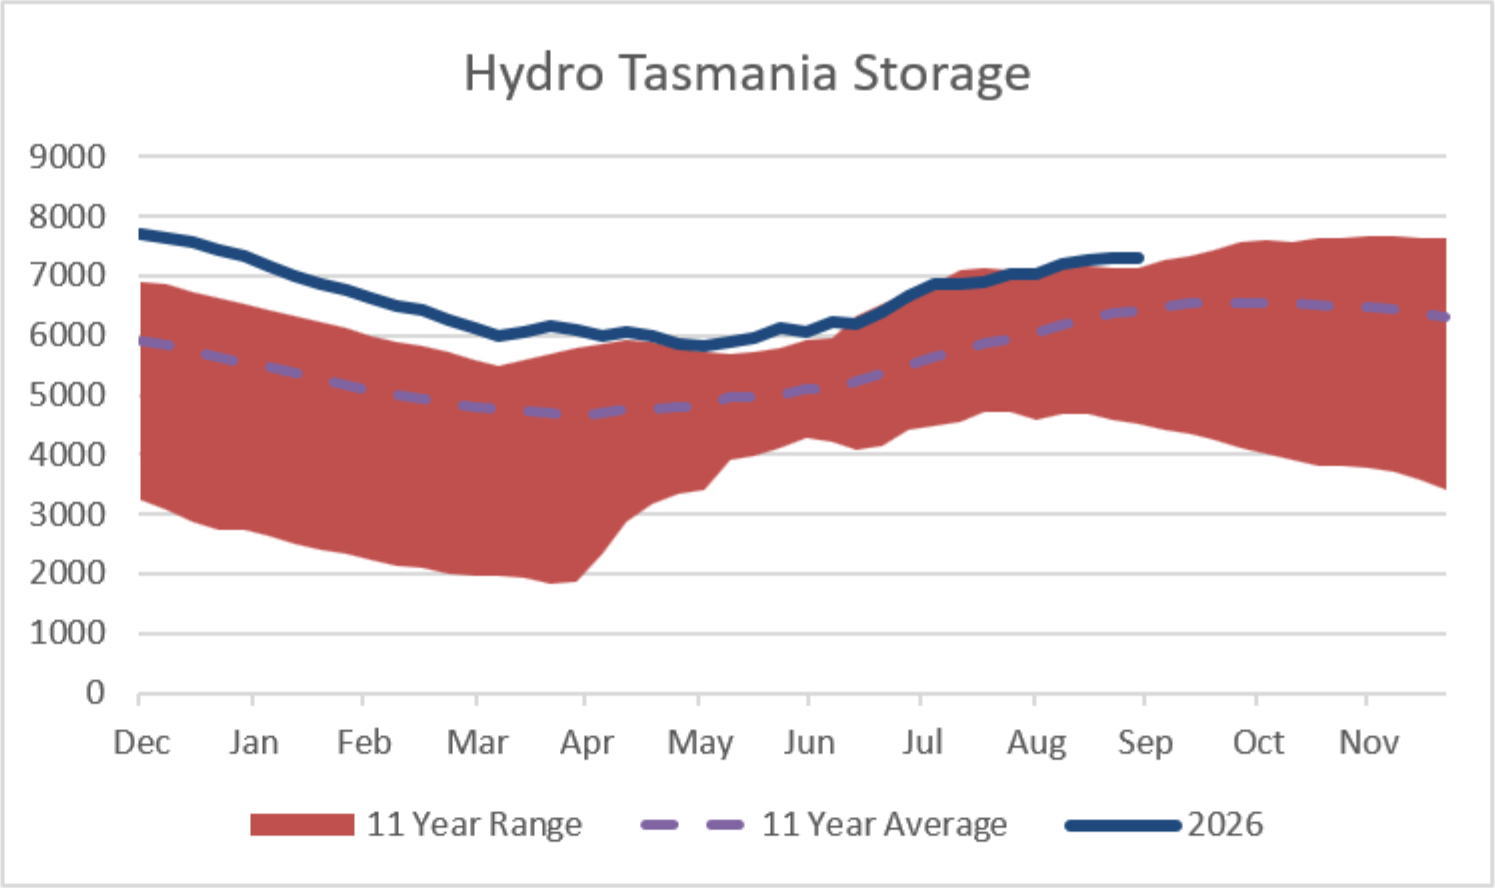
Hydro generation was again significantly lower in September than in August and was well below the lowest level recorded at this time of year during the past 11 years, as shown below.
Storage in Hydro Tasmania’s lakes increased again through September. Storage ended the month at 7,287GWh (50% full), an increase of 242GWh over the month. This is 7% higher than the level recorded at the same time last year and slightly more than the maximum level seen at this time of year in the last 11 years, as shown in the following chart.
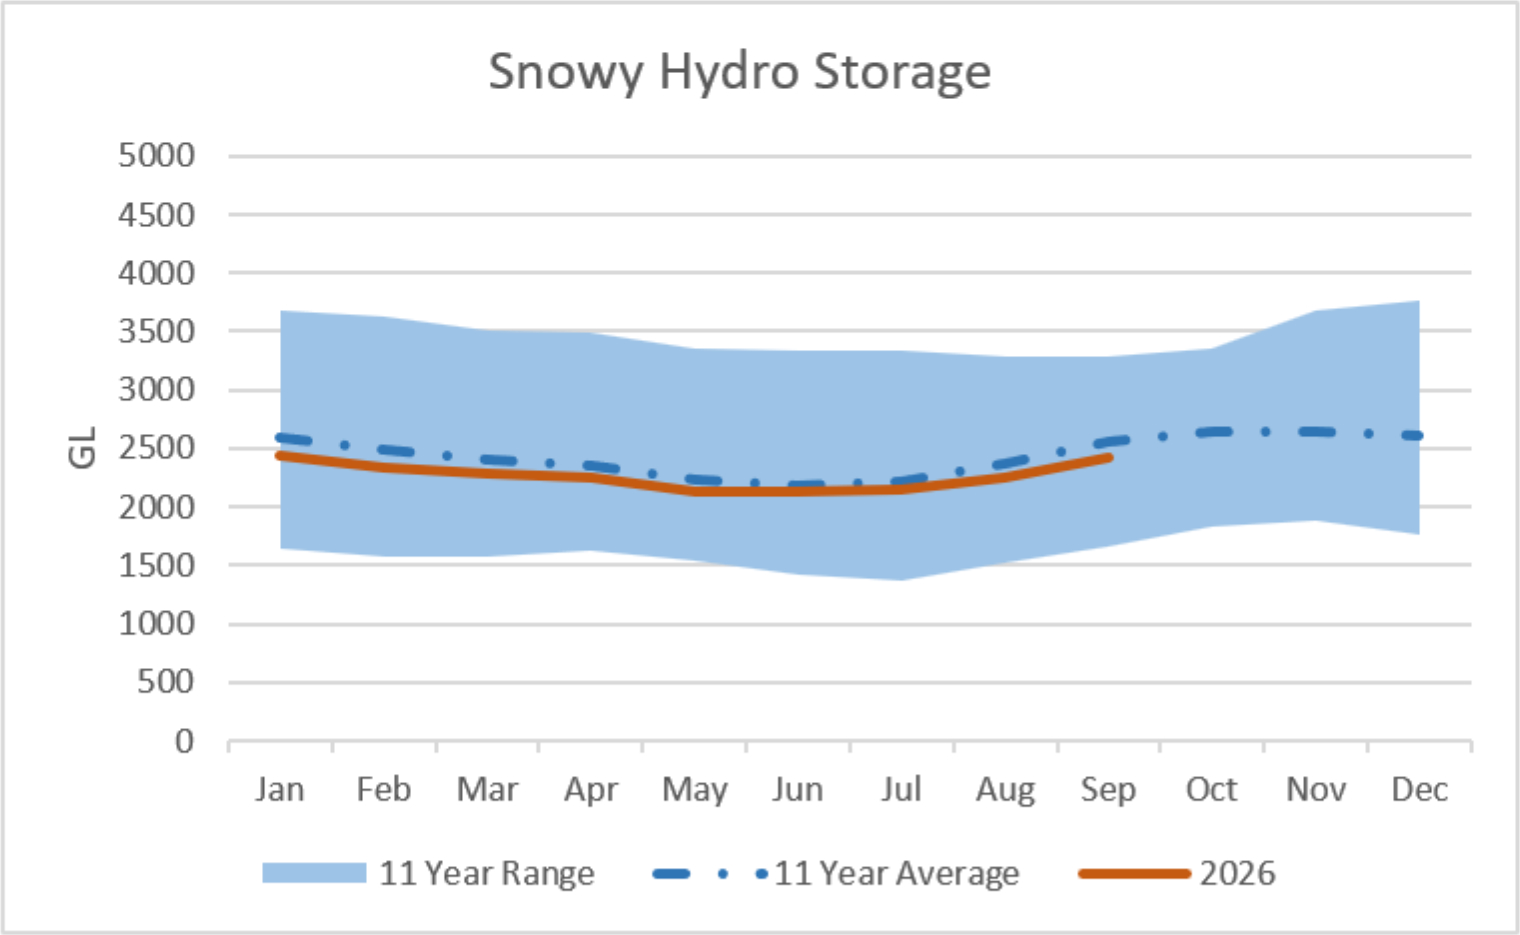
Snowy Hydro’s storage increased through September. Snowy finished the month 46% full, with storage of 2,426 GL– a 7.8% increase over the month. Levels remain close to the 11-year average for this time of year as shown in the following chart.
Climate outlook overview (from BOM)
The long-range forecast for October to December shows:
- Rainfall is likely to be above average across much of the west and central regions, below average in the far north and south-east.
- Daytime temperatures are likely to be above average for most of Australia.
- Overnight temperatures are likely to be above average across Australia.
New Renewable Generation (Excluding Hydro)
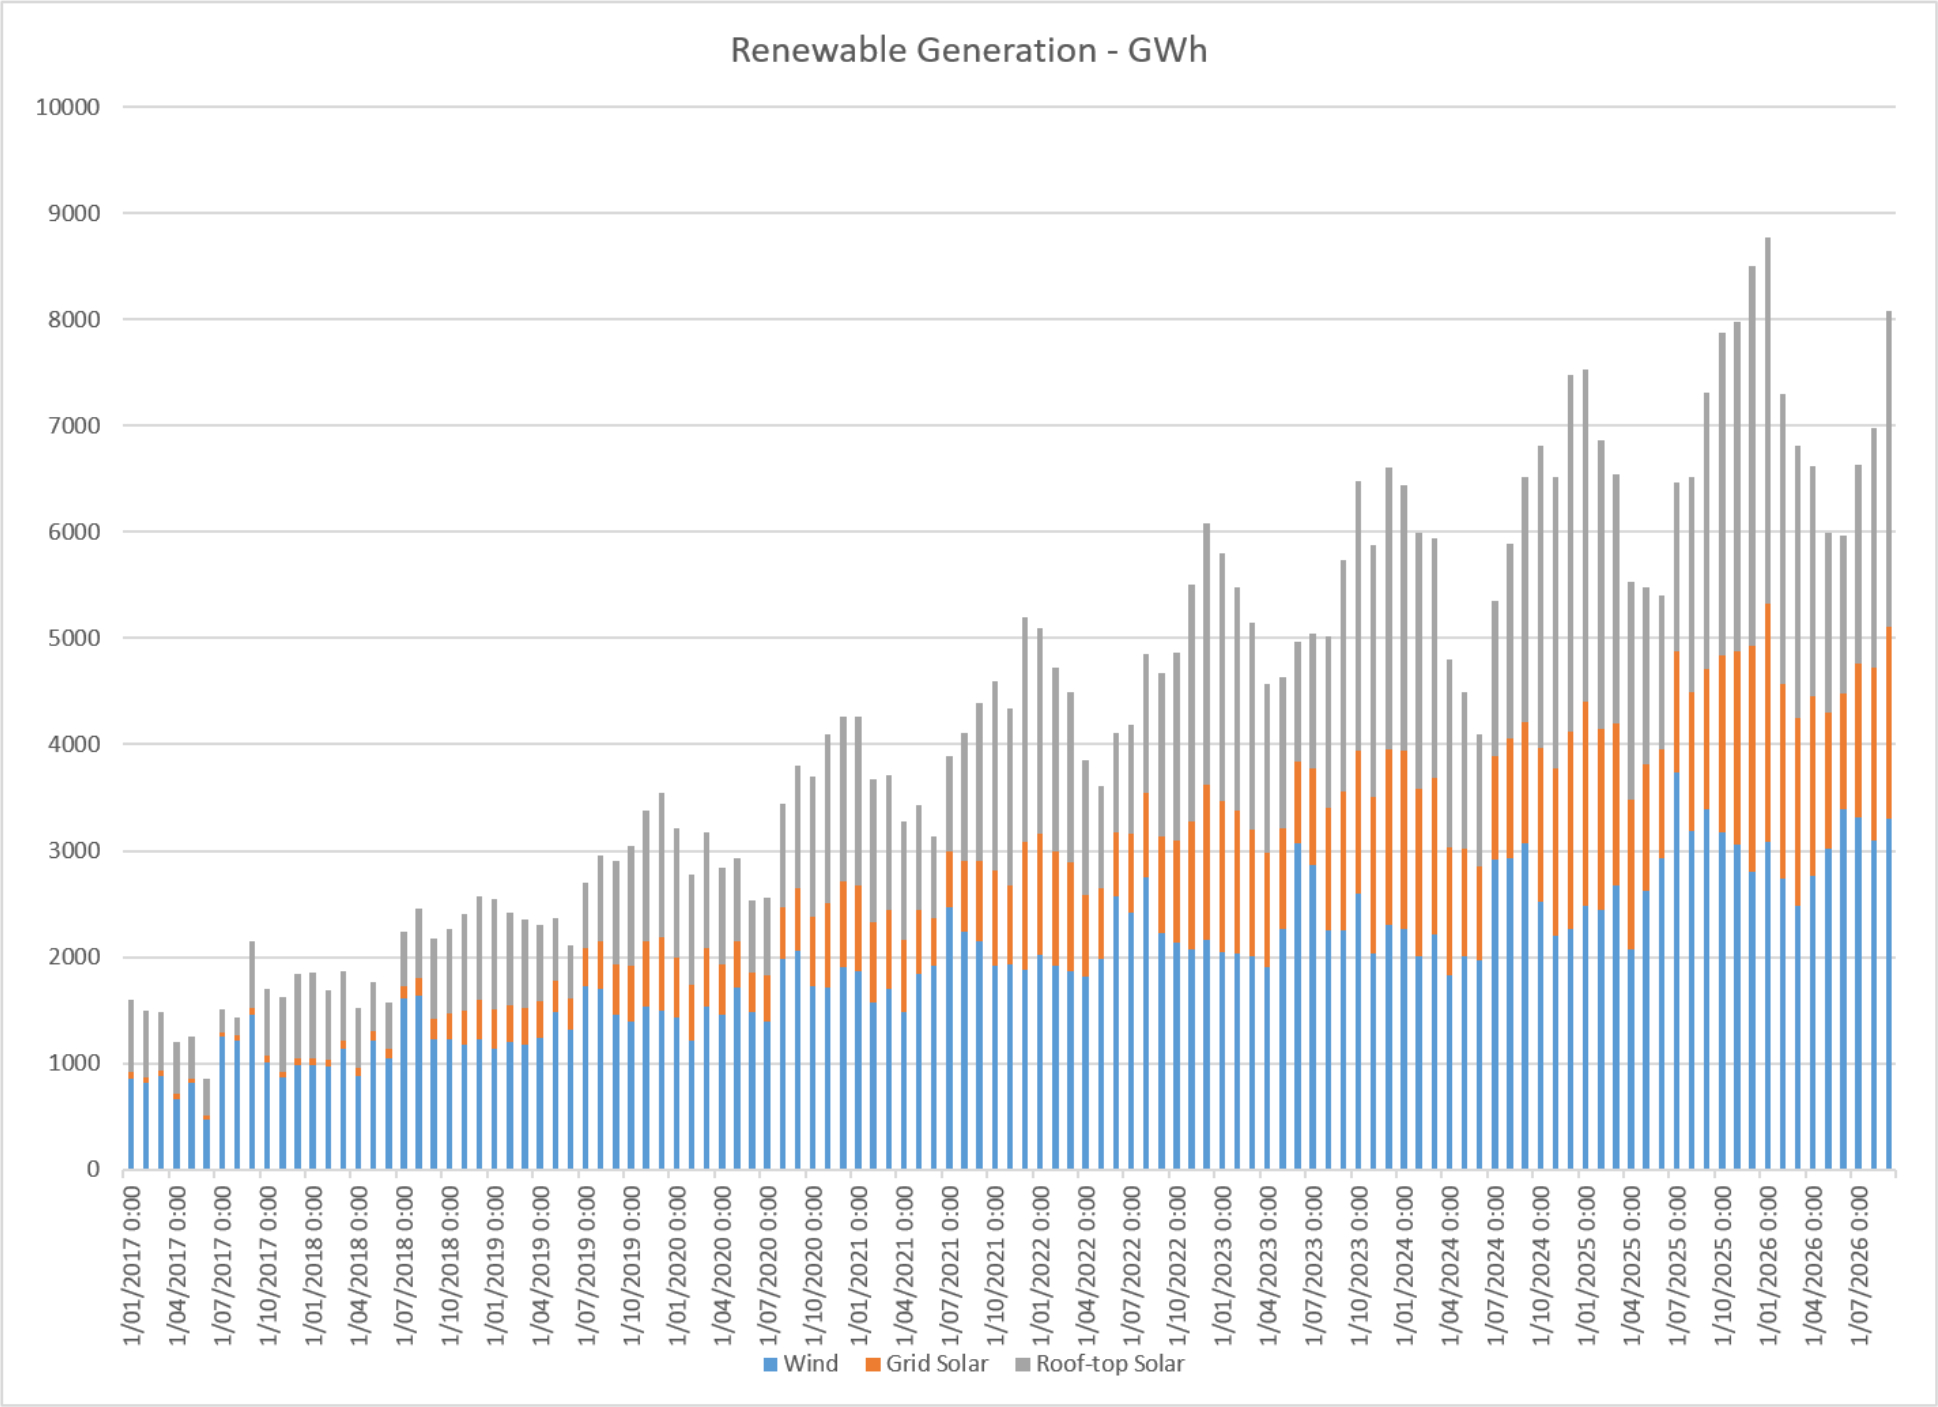
Total renewable generation (wind and solar, including roof-top solar) in September was 8,080GWh – an increase of 16% from last month’s level and 10% above the same month last year. Wind generation was up 7% from last month’s level and 3% below September 2025. Utility-scale solar generation was up 11% from August’s level and up 37% over the same month last year.
The following chart shows the monthly energy produced for each of these renewable types since 2017.
The Electricity Futures Market
Futures prices increased through September in all States, across all calendar years.
In NSW CAL27 was up 6% at $90. CAL28 was also up 6% at $92, while CAL29 was up 3% ending the month at $99.
Calendar Year Contracts for New South Wales

QLD prices in CAL27 were up 4% at $79 while CAL28 was up 5% ($81). CAL29 ended the month up 7.5% at $86.5.
Calendar Year Contracts for Queensland

VIC futures prices for CAL27 increased 5% to $66, while CAL28 was also up 5% at $77. CAL29 ended the month up 4% at $87.
Calendar Year Contracts for Victoria

SA has less liquidity in the futures markets than other States, so changes tend to be lumpier and less a true reflection of the underlying market. For completeness we have included the graph below.
Calendar Year Contracts for South Australia

The Gas Market
International LNG netback prices have increased because of the conflict in the Middle East. Prices in September increased another 17% to $30.24/GJ. Forecast average prices are currently $21.70/GJ for 2026 and $22.90/GJ for 2027. (Note that netback prices are indicative of international prices – they are produced by the ACCC and quoted in Australian dollars. They are net of the estimated cost of converting pipeline gas in Australia to LNG, hence the term ‘netback’)

Domestic spot gas prices increased slightly in September. The following graph shows the 30-day rolling average price at the Wallumbilla Gas Supply Hub, which ended the month at $10.90/GJ, up 2.5% from August levels. This remains well below the LNG netback price. Prices are 10% below what they were the same time last year.

Gas storage at the key Iona storage facility stopped declining during September. Storage increased to 13.3PJ – a 3% rise over the month. Storage remains close to the average level we have seen at this time of year for the past 9 years.

LPG is an important fuel for many large energy users, particularly in areas where reticulated natural gas is not available. The contract price of LPG is typically set by international benchmarks such as the Saudi Aramco LPG prices, which are normally quoted in US dollars per metric tonne.
The following graph shows the Saudi Aramco LPG pricing for the last 5 years as well as forecast pricing for the year and a half ahead. The conflict in the Middle East caused prices to spike from April to June but they fell steeply in July before rising again in August. Futures prices increased through September.

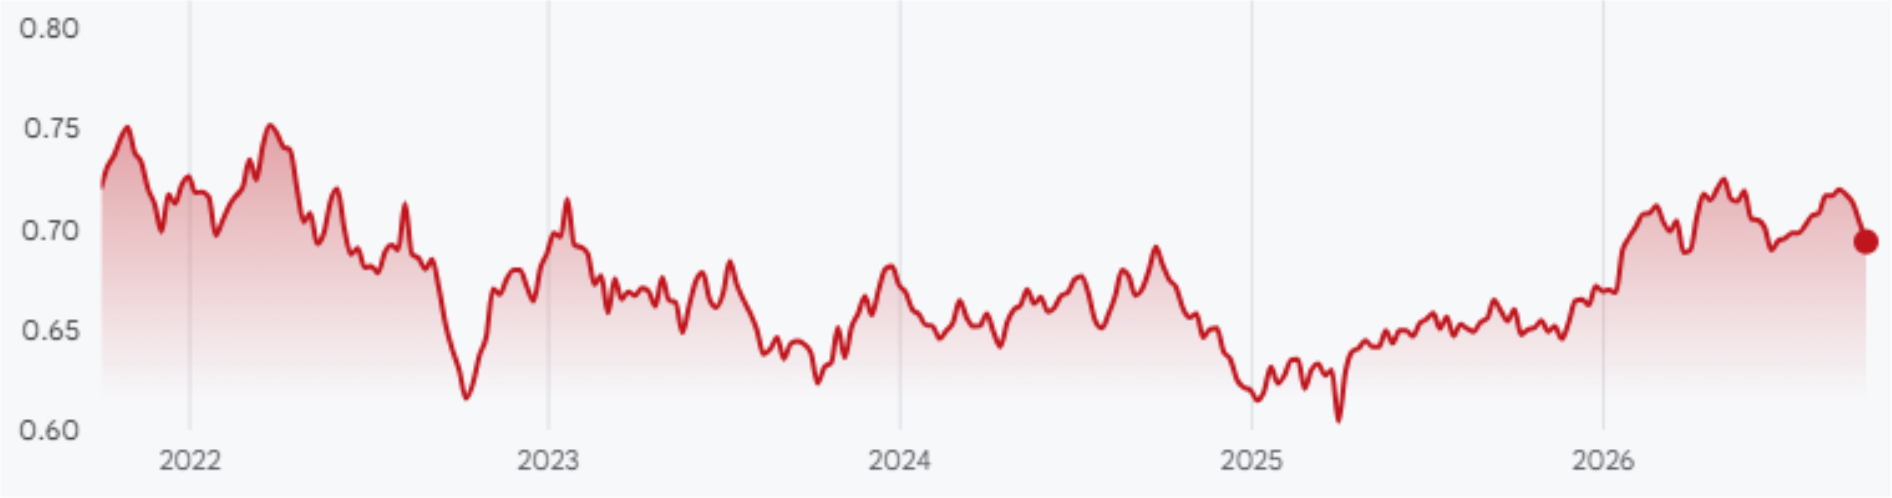
The other main contributing factor to LPG prices in Australia is the exchange rate against the USD. The AUD/USD exchange rate was around 0.72 at the start of the month and declined steadily to end at 0.69. This remains above the average levels seen in recent years. The recent decline in the exchange rate would tend to increase LPG prices when expressed in Australian dollars.
The Coal Market
The conflict in the Middle East has contributed to an increase in coal prices along with other international energy commodities. To date the impact has not been as great as that observed during the initial years of the Ukraine war. Prices remained relatively flat for most of September but ended the month at $149/tonne, an increase of 5%. The following graph shows prices over the past 10 years.

International coal prices continue to be an important driver of electricity prices, especially in the states most reliant on black coal generation, namely Queensland and New South Wales.
Environmental Certificates
The following graph shows environmental certificate spot prices over the last 6 years.
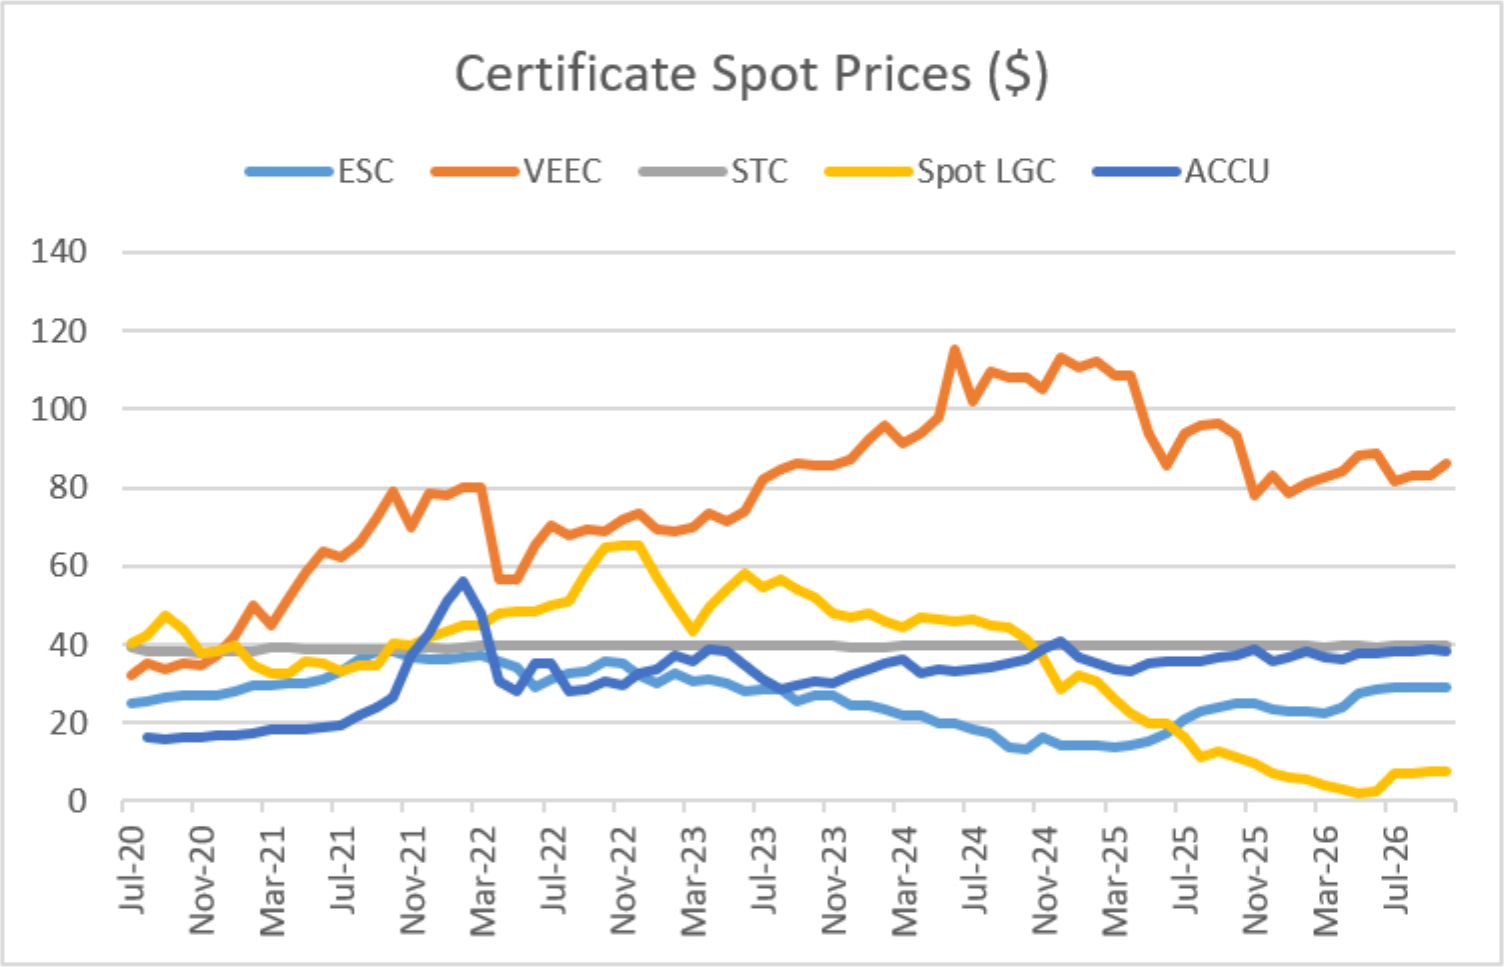
VEEC prices increased in September – up 3% to $86. ESCs were up 1% at $29.25. ACCUs and Spot LGCs were down 1% at $38.4 and $7.65 respectively. STCs were unchanged at $39.65.
Over recent months, future-dated LGC prices have increased from historically low levels. Prices for all future years currently sit within a narrow band of $7.00 to $8.25 per certificate and are down by approximately 6% from last month.

About this Report
This energy market summary report provides information on wholesale price trends for all regions within the National Electricity Market (NEM) and environmental scheme certificates.
Please note that all electricity prices are presented as a $ per MWh price and all certificate prices as a $ per certificate price.
All NEM spot prices are published by the Australian Energy Market Operator (AEMO). Futures contract prices are sourced from ASX.
Further information can be found at the locations noted below.
- NEM Spot market – AEMO publishes a range of detailed information which can be found here: https://aemo.com.au/Electricity/National-Electricity-Market-NEM/Data-dashboard
- Weather and Climate data – The Bureau of Meteorology publishes a range of weather related information which can be found here: http://www.bom.gov.au/climate/
Disclaimer
This document has been prepared for information and explanatory purposes only and is not intended to be relied upon by any person. This document does not form part of any existing or future contract or agreement between us. We make no representation, assurance or guarantee as to the accuracy of information provided. To the maximum extent permitted by law, none of Smart Power Utilities Ltd, its related companies, directors, employees or agents accepts any liability for any loss arising from the use of this document or its contents or otherwise arising out or, or in connection with it. You must not provide this document or any information contained in it to any third party without our prior consent.
© Copyright, 2026. Smart Power Utilities Ltd ABN 72 121 464 864


